Insurance lowballing your totaled car?
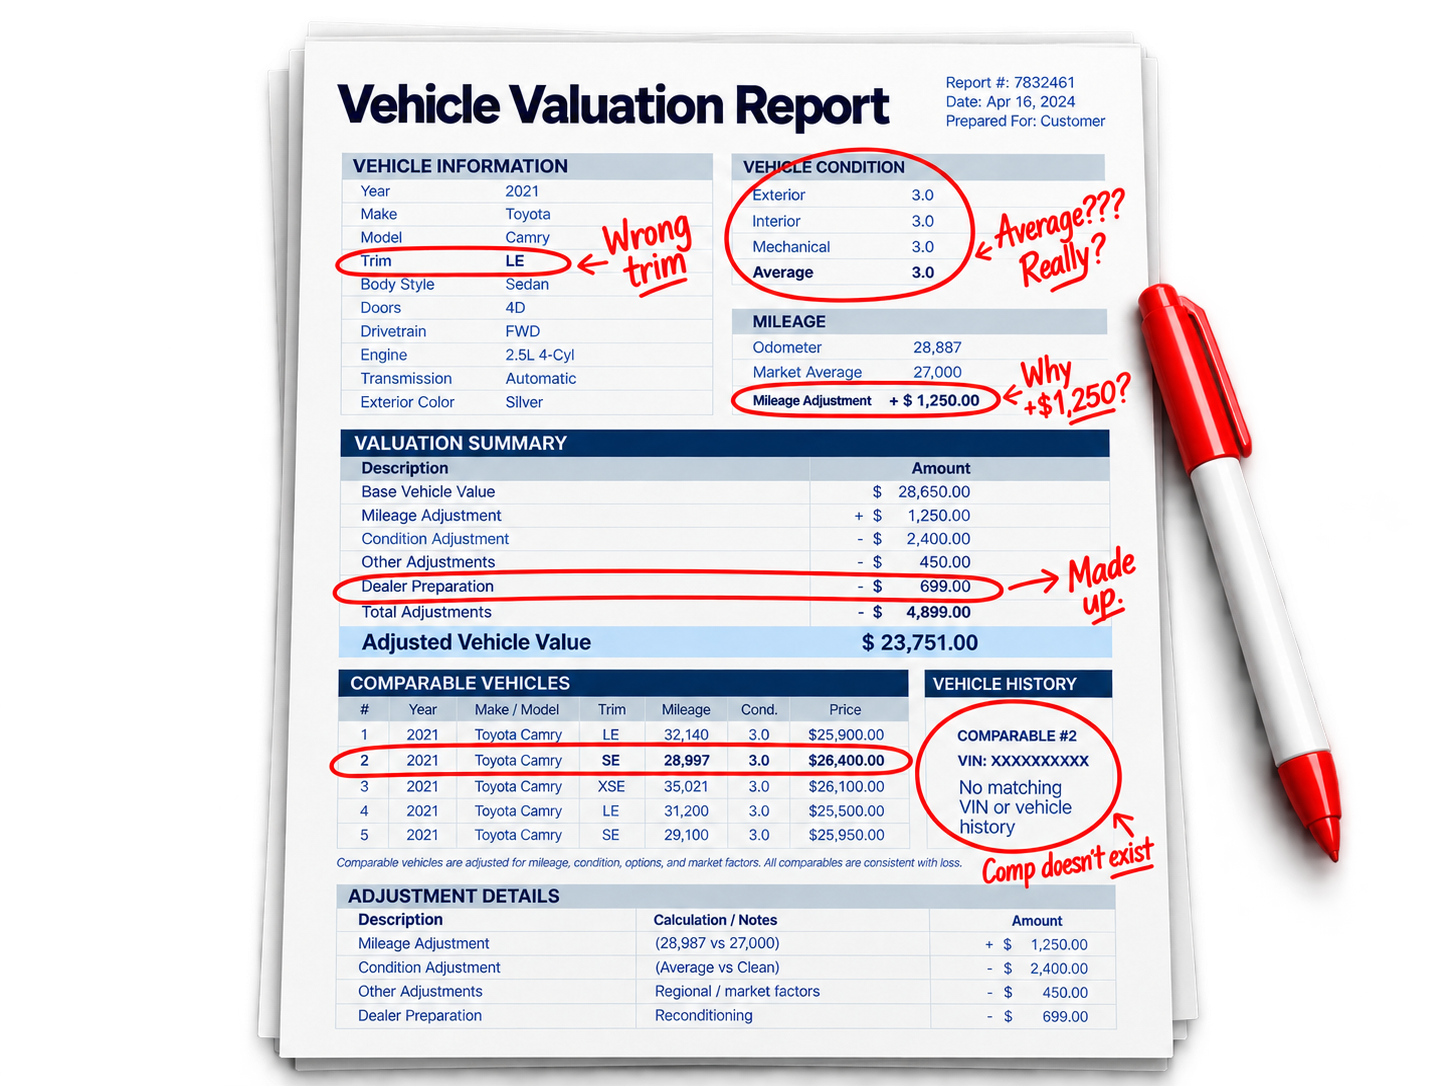
I review total loss valuations and research what your vehicle was worth before the accident. Send me your insurance company’s report, and I’ll give you a realistic value range and tell you whether I think it’s worth challenging.
Send me your insurer’s valuation. I’ll research what your vehicle was worth and tell you whether I think the offer is worth challenging.
$500 flat. No payment upfront.
Includes market research, a detailed appraisal report, negotiations with the insurer’s appraiser, and the full appraisal-clause process.
If the completed appraisal-clause process doesn’t increase your vehicle-only ACV by at least $1,000, you owe us no appraisal fee.
Full pricing and umpire-fee detailsNot sure if the offer is too low?
Send me your insurer’s valuation and a few details about your vehicle. I’ll research the market and tell you whether I think an appraisal makes sense.
No obligation. If the offer looks reasonable, I’ll tell you that too.
Comparable vehicles for sale
We search major automotive marketplaces like Cars.com, Autotrader, CarGurus & more for comparable vehicles currently on the market.
Recent sales, when relevant
We research past sales through platforms like Bring a Trailer, Cars & Bids, Classic.com & more, when appropriate.
Private-party listings, when relevant
We examine privately listed vehicles on marketplaces like Facebook Marketplace, Craigslist & more, when appropriate.
Dealer inventory
We search dealer inventories and verify listing details, availability and comparability where possible.
Equipment and vehicle verification
We verify the VIN, trim, engine, drivetrain, mileage and equipment. Factory build information helps confirm options when available.
Industry valuation references
We cross-check the market against Kelley Blue Book, J.D. Power, Black Book and Manheim data when useful.
A realistic value range
We estimate a defensible ACV range, compare it with the insurer’s offer, and recommend moving forward only when the likely benefit justifies the cost.
I’ve been through this myself. Twice.
In 2012, I lost my mint-condition 1992 Toyota Pickup in a rollover on an icy mountain road. In 2023, my 1998 Dodge Ram with the 12-valve Cummins was destroyed in an engine fire. Both times, the insurance company’s valuation was well below what I knew my vehicle was worth.
I fought those valuations and eventually got fair settlements, but neither dispute was easy. That experience is why I started helping other people dispute total loss valuations.
Today I research vehicle values, prepare independent appraisals and work with the insurer’s appraiser to reach a fair value when the policy allows it. I won’t inflate a number just to make a case look better. I want the value to be supported by actual evidence.
“We all pay a lot of money to insure our vehicles. When we have a covered loss, it’s only fair that the insurance company pays what the vehicle was actually worth.”
What customers have said about working with us.
These reviews were left by customers of the appraisal company behind Don’t Get Lowballed, including people we advised against hiring us.
“My insurance company originally offered about $8k. With an easy email and a bit of info, they got me $11k, and all done within less than a week.”
Jeff H. · Google review
“What’s really appreciated is that he was upfront and honest about my situation and did not try to persuade me to pay for an appraisal where I would get less than the report cost.”
Steven L. · Google review
“Dustin stayed in contact every step of the way, letting me know what I needed to do and even providing helpful wording to use when in contact with my insurer.”
Mariah W. · Google review
“Gave me an honest appraisal and could not provide me a better rate than my insurance. He could have taken my money and promised me more but didn’t and that shows his character.”
Kolin A. · Google review
“Seamless process and very timely. I received almost 6k more before taxes because of their due diligence.”
Jennifer B. · Google review
“Dustin was very quick to respond and did exactly what he said he would. Ended up getting us several thousand dollars more than State Farm was initially offering.”
Jeff L. · Google review
If the numbers support a dispute, here’s what happens next.
The free review comes first. If an appraisal makes financial sense and your policy permits it, we handle the independent valuation and negotiations with the insurer-appointed appraiser.
We review your valuation for free.
Send the insurance company’s offer and basic information about your vehicle. We research the market and tell you whether we believe the insurer’s vehicle value is low enough to justify challenging it. Some offers are reasonable. I’ll tell you that too.
You invoke the appraisal clause.
This is a provision in many insurance policies that lets you dispute the vehicle’s value using independent appraisers. I’ll provide the paperwork and instructions. The clause generally applies to your own policy, not another driver’s insurer.
We prepare an independent appraisal.
I’ll put together a detailed, USPAP-compliant report with comparable vehicles, equipment, mileage, vehicle history, adjustments and supporting market evidence. The goal is a defensible value, not just a higher number.
We negotiate with the insurer’s appraiser.
We exchange valuations, discuss the evidence and try to agree on the vehicle’s pre loss actual cash value. If we can’t agree, the policy provides for an umpire. I’ll keep you informed and help take the negotiations off your plate.
Full pricing and guarantee terms.
The initial second opinion is free. If you choose to proceed, these are the terms of the appraisal service.
No percentage of your increase
Full appraisal-clause service included. Independent market research, a detailed appraisal report, exchange and negotiation with the insurer-appointed appraiser, and working with an umpire if needed.
If the completed appraisal-clause process does not increase your vehicle-only ACV by at least $1,000, you owe us no appraisal fee. The guarantee is assessed at completion, including an umpire award when applicable.
An umpire, if needed, charges separately. The policy typically requires the two parties to split that expense. Any potential umpire fee is discussed before proceeding. The $500 fee covers our services, not third party umpire charges. Terms are set out in your appraisal agreement.
Request a free second opinionA few things people ask.
Does it cost anything to have you look at my offer?
No. The initial review is free. Send your vehicle details and the insurance valuation. We’ll research the market and let you know whether the offer looks worth challenging.
What if the insurer is already offering a fair amount?
I’ll tell you that. Some cases simply don’t have enough market support for an increase, and I’d rather say so upfront than have you spend money on an appraisal you don’t need.
Can the insurer refuse to change its number?
If your policy includes an applicable appraisal clause, the vehicle value is determined through the process set out in your policy. Each side appoints an appraiser, and an umpire can be involved if they cannot agree. I can’t promise a particular result.
Do you handle claims in my state?
We handle total loss appraisals remotely where the appraisal process is available under the applicable insurance policy and state requirements. Send us your claim information, and we’ll confirm whether we can help.
Does this work for a third party claim?
Usually not through the appraisal clause. That clause is generally part of your own insurance policy. If another driver’s insurer is handling the claim, I can explain the limitation, but the full appraisal-clause process generally isn’t available against that insurer.
Want us to review your insurer’s valuation?
Send the valuation report and your vehicle details. We’ll research the market and give you a candid assessment. If we recommend an appraisal, the fee is $500 flat, with no payment upfront.
Go to the free case reviewDon’t Get Lowballed is operated by Fair Auto Appraisals LLC